Canada’s 10 Best Travel Credit Cards
Last updated February 13, 2026
Best Travel Credit Cards
No matter how often you travel or what your style is, travel credit cards are great for earning rewards, making points bookings, and enhancing your travel experience with elite benefits.
Read on to learn more about our recommendations for the best travel credit cards in Canada.
Compare our picks
Best Overall Travel Credit Card
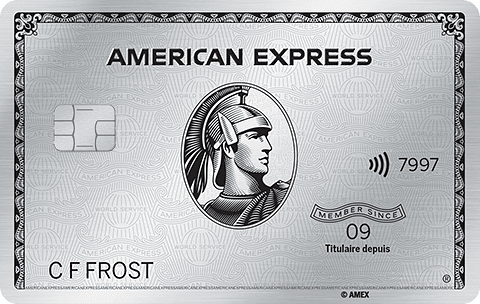
American Express Platinum Card
- Annual fee
- $799
- Welcome bonus
- 110,000 Membership Rewards points
- First-year value
- $1,581
- Top earn rate
- 2x Travel
RBC® Avion Visa Infinite Privilege†
- Annual fee
- $399
- Welcome bonus
- 100,000 Avion points
- First-year value
- $826
- Top earn rate
- 1.25x All Purchases
TD® Aeroplan® Visa Infinite Privilege* Card
- Annual fee
- $599
- Welcome bonus
- 100,000 Aeroplan points
- First-year value
- $701
- Top earn rate
- 2x Air Canada
Best Mid-Fee Travel Credit Card
- Annual fee
- $120
- Welcome bonus
- 70,000 Avion points
- First-year value
- $1,080
- Top earn rate
- 1.25x Travel1, 2
Scotiabank Passport® Visa Infinite Privilege* Card
- Annual fee
- $599
- Welcome bonus
- 80,000 Scene+ points
- First-year value
- $451
- Top earn rate
- 6x Scene Plus Travel Portal
Best Travel Credit Card for Insurance
National Bank® World Elite® Mastercard®
- Annual fee
- $150
- Welcome bonus
- –
- First-year value
- –
- Top earn rate
- 5x Groceries
WestJet RBC® World Elite Mastercardǂ
- Annual fee
- $139
- Welcome bonus
- 70,000 WestJet points
- First-year value
- $536
- Top earn rate
- 2x WestJet
BMO VIPorter World Elite®* Mastercard®*
- Annual fee
- $199First Year Free
- Welcome bonus
- 70,000 VIPorter points
- First-year value
- $1,320
- Top earn rate
- 3x Porter
Best Travel Card for Business Owners
American Express Aeroplan Business Reserve Card
- Annual fee
- $599
- Welcome bonus
- 95,000 Aeroplan points
- First-year value
- $1,064
- Top earn rate
- 3x Air Canada
Best Travel Credit Card for Beginners
CIBC Aventura® Visa Infinite* Card
- Annual fee
- $139First Year Rebate
- Welcome bonus
- 45,000 Aventura Points
- First-year value
- $480
- Top earn rate
- 2x CIBC Rewards Travel
Best Overall Travel Credit Card
First-year value
$1,581
Annual fee: $799
• Earn 80,000 points upon spending $10,000 in the first 3 months
• Plus, earn 30,000 points Upon making a purchase between months 15 and 17 of Cardmembership
Earning rates
Key perks
- $200 annual travel credit
- $200 annual dining credit
- $100 NEXUS credit
- Unlimited Priority Pass lounge access
- Marriott Bonvoy Gold Elite status
- Platinum Concierge
Annual fee: $799
• Earn 80,000 points upon spending $10,000 in the first 3 months
• Plus, earn 30,000 points Upon making a purchase between months 15 and 17 of Cardmembership
Earning rates
Key perks
- $200 annual travel credit
- $200 annual dining credit
- $100 NEXUS credit
- Unlimited Priority Pass lounge access
- Marriott Bonvoy Gold Elite status
- Platinum Concierge
For premium rewards and benefits, the American Express Platinum Card reigns supreme.
Like its counterpart for business owners, the personal Platinum Card earns Membership Rewards points, the most flexible transferable rewards in Canada. You can get a strong welcome bonus when you apply through a refer-a-friend link.
In particular, Canadians can transfer MR points to Air Canada’s Aeroplan program, supplementing the points earned on other credit cards which carry the Aeroplan label. The best long-haul premium cabins on Air Canada’s partners can cost quite a few points, and cards with such a big welcome bonus are few and far between, so the Platinum Card is a great way to get you there more quickly.
If you spend a lot on dining and travel, you’ll earn 2 MR points per dollar spent, along with 1 MR point per dollar spent on all other purchases.
However, perhaps more so than everyday spending, the Platinum Card truly shines when it comes to airport lounges, and that access changes on January 1, 2027.
Until December 31, 2026, you’ll get unlimited visits to Priority Pass lounges for you and one guest, as well as Plaza Premium lounges and American Express Centurion Lounges for you, your spouse, and two children under the age of 21 or one travelling companion.
From January 1, 2027, you’ll get six complimentary visits a year each to Priority Pass and Plaza Premium lounges, and a guest’s visit counts as one of them. Each eligible supplementary cardholder gets two visits a year to each. Spend $20,000 on the card in a calendar year, and your visits are unlimited again for the rest of that year and all of the next. Centurion Lounges and the rest of Amex’s Global Lounge Collection stay unlimited.
After that date, the Platinum Card stays our best overall travel credit card if you’ll spend $20,000 a year on it. It’s also our pick if you don’t rely on Priority Pass and Plaza Premium lounges.
For an elevated hotel experience, the card grants automatic Marriott Bonvoy Gold Elite status and Hilton Honors Gold status.
This would be useful if, say, your priority is the Marriott Bonvoy program and you maintain a higher status there like Platinum or Titanium, but you like to ensure a few token benefits for those odd stays at other hotel brands.
Finally, the Platinum Card is among the best-in-class for travel insurance, offering higher payouts and wider-ranging coverage than most other credit cards.
Best Premium Visa Travel Card
First-year value
$826
Annual fee: $399
• Earn 35,000 points on approval
• Earn 20,000 points upon spending $5,000 in the first 6 months
• Earn 45,000 points on card anniversary in the first 12 months
Earning rates
Key perks
- 6 Visa Airport Companion lounge visits per year
- Priority security at Toronto Billy Bishop, Montreal, Ottawa
- Visa RSVP Diamond at 60+ Sandman/Sutton hotels
- Troon Rewards Platinum (20% off at 150+ golf courses)
- Transfer to British Airways Avios, Cathay Asia Miles, WestJet, American Airlines
- DoorDash DashPass for 12 months
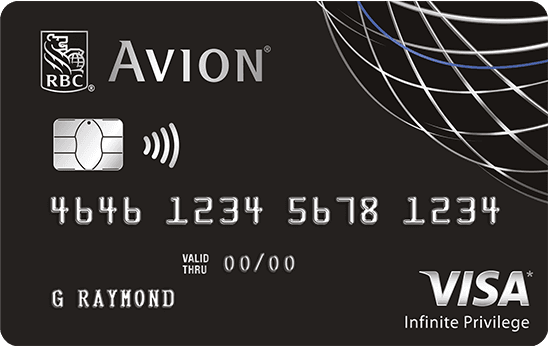
The RBC® Avion Visa Infinite Privilege† is RBC's top-tier travel card, and it delivers a unique value proposition that's hard to find elsewhere.
The card earns RBC Avion points at 1.25x on all purchases, but where it truly shines is in redemptions: you can redeem at 2 cents per point on business and first class bookings through RBC's travel portal, doubling the standard 1 cent per point rate on economy flights.
That 2-cents-per-point rate on business and first class bookings is a standout feature. The card also comes with six Visa Airport Companion lounge visits per year, priority airport services at select Canadian airports, and comprehensive travel insurance.
Avion points can be transferred to partners including British Airways Avios, Cathay Pacific Asia Miles, American Airlines AAdvantage, and WestJet Rewards, giving you solid flexibility for award bookings. The $399 annual fee is significant, but if you regularly book premium cabins, the value proposition can be compelling.
Best Visa for Aeroplan
First-year value
$701
Annual fee: $599
• Earn 20,000 points on first purchase
• Earn 30,000 points upon spending $12,000 in the first 6 months
• Earn 50,000 points on card anniversary upon spending $24,000 in the first 12 months
Earning rates
Key perks
- Unlimited Maple Leaf Lounge access + 1 guest
- 6 Visa Airport Companion lounge visits per year
- Priority check-in, boarding, and baggage handling for cardholder + up to 8 companions
- Priority security at Toronto Billy Bishop, Montreal, Ottawa
- Free first checked bag for cardholder + up to 8 companions
- 1,000 SQC per $5,000 spend toward Aeroplan Elite Status (up to 25,000 SQC/year)
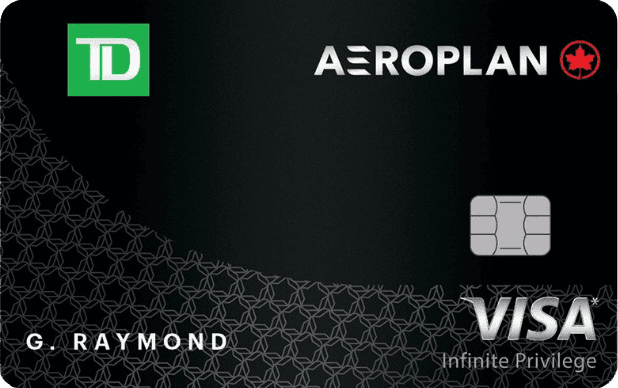
If you’d prefer to avoid the challenges of Amex’s limited acceptance, the TD® Aeroplan® Visa Infinite Privilege* Card is another great choice.
New cardholders can receive a very competitive welcome bonus, often on par with the Business Platinum Card from American Express. However, with lower or more drawn-out spending requirements, you're at less of a risk of missing out entirely in case your spending fluctuates or you accidentally miss a deadline.
Beyond that, you’ll earn 2x Aeroplan points on Air Canada flights and vacations, 1.5x Aeroplan points on gas, groceries, dining, food delivery, and travel, and a strong base rate of 1.25x Aeroplan points on all other purchases.
As for perks, the card has all of the same premium Aeroplan benefits as the American Express Reserve cards, with the added benefit of a DragonPass membership with six free lounge visits per year.
If the annual fee is too steep ($599, or $699 from the first annual fee due on or after January 25, 2027), consider the TD® Aeroplan® Visa Infinite* Card instead. It has a lower annual fee and a smaller welcome bonus, and you’ll also have a lower earning rate, fewer Aeroplan benefits, and weaker insurance.
Best Mid-Fee Travel Credit Card
First-year value
$1,080
Annual fee: $120
• Earn 35,000 points on approval
• Earn 20,000 points upon spending $5,000 in the first 6 months
• Earn 15,000 points on card anniversary in the first 12 months
Earning rates
Key perks
- Transfer to British Airways Avios, Cathay Asia Miles, WestJet, American Airlines
- DoorDash DashPass for 12 months
- Petro-Canada 3¢/L savings + 20% bonus Petro-Points
Annual fee: $120
• Earn 35,000 points on approval
• Earn 20,000 points upon spending $5,000 in the first 6 months
• Earn 15,000 points on card anniversary in the first 12 months
Earning rates
Key perks
- Transfer to British Airways Avios, Cathay Asia Miles, WestJet, American Airlines
- DoorDash DashPass for 12 months
- Petro-Canada 3¢/L savings + 20% bonus Petro-Points
The RBC® Avion Visa Infinite† gives you RBC Avion points at their most useful level for a mid-range fee. For $120 a year, you get the same Avion Elite access as the RBC® Avion Visa Infinite Privilege†, which costs $399.
That access is the reason to get the card. You can transfer your points to British Airways Avios, Cathay Asia Miles, American Airlines AAdvantage and WestJet Rewards, or book flights on RBC’s own fixed-points chart. If you’d rather keep things simple, your points are worth 1 cent each towards travel booked with RBC. Our valuation of Avion points is 2 cents each.
You’ll earn 1.25 Avion points per dollar on travel and 1 point per dollar on everything else, so this isn’t the card for fast earning on groceries or dining. The insurance is lighter too: emergency medical coverage lasts 15 days per trip (three days if you’re 65 or older), and trip cancellation covers up to $1,500 per person.
It suits you if you want flexible travel points for a modest fee, with a personal income of $60,000 or a household income of $100,000. If you book business class often and want lounge visits, the Avion Visa Infinite Privilege earns more on everyday spending and adds both.
Best for Travelling Abroad
First-year value
$451
Annual fee: $599
• Earn 30,000 points upon spending $3,000 in the first 3 months
• Earn 30,000 points upon spending $20,000 in the first 6 months
• Plus, earn 20,000 points upon spending in month 13
Earning rates
Key perks
- No foreign transaction fees
- 10 Visa Airport Companion lounge visits per year
- Priority security at Toronto Billy Bishop, Montreal, Ottawa
- Visa RSVP Diamond at 60+ Sandman/Sutton hotels
- Troon Rewards Platinum (20% off at 150+ golf courses)
- $250 annual travel credit via Scene+ Travel
Most Canadian credit cards charge a foreign transaction fee on purchases in another currency. The Scotiabank Passport® Visa Infinite Privilege* Card doesn’t, and it earns well on what you spend on a trip.
You’ll earn 3 Scene+ points per dollar on travel, 2 points per dollar on dining and entertainment, and 1 point per dollar on everything else, at home or abroad. When you book hotels, car rentals and activities through Scene+ Travel, you’ll earn 6 points per dollar. Our valuation of Scene+ points is 1 cent each.
Each year, you also get 10 Visa Airport Companion lounge visits and a $250 travel credit, plus Avis President’s Club membership. Emergency medical coverage goes up to $5 million for trips of up to 31 days (10 days if you’re 65 or older), and trip cancellation covers up to $2,500 per person.
The catch is the $599 annual fee, though Scotiabank takes $150 off if you hold its Ultimate Package chequing account. You’ll also need a personal income of $150,000, a household income of $200,000 or $400,000 in assets under management. If that’s out of reach, the Scotiabank Passport® Visa Infinite +* Card also has no foreign transaction fees, with six lounge visits a year for a $150 fee.
Best Travel Credit Card for Insurance
Annual fee: $150
Earning rates
Key perks
- Airport lounge access
Annual fee: $150
Earning rates
Key perks
- Airport lounge access
The National Bank® World Elite® Mastercard® is the card to hold if insurance matters most on your trips. Trip cancellation covers up to $2,500 per person, even on award tickets, as long as you charge part of the trip’s cost, such as the taxes and fees, to the card. Trip interruption covers up to $5,000 per person.
Emergency medical coverage goes up to $5 million and lasts 60 days per trip if you’re 54 or younger, 31 days from 55 to 64 and 15 days from 65 to 75. A trip longer than that isn’t covered at all, and there’s no medical coverage from age 76. You’re also covered for flight delays (up to $500 after four hours), lost, damaged or delayed bags (up to $1,000 per person, of which up to $500 for a delay of six hours or more, when the whole fare is on the card) and collision damage on rental cars.
Beyond insurance, the card earns 5 À la carte Rewards points per dollar on groceries and dining, on up to $2,500 in total monthly spending (2 points per dollar after that). It also refunds up to $150 a year in travel expenses, and if you fly from Montréal-Trudeau, you get unlimited visits to the National Bank Lounge there.
The annual fee is $150, and you’ll need a personal income of $80,000 or a household income of $150,000. If you’d rather have lounge visits around the world, the Scotiabank Passport® Visa Infinite Privilege* Card also carries $5 million of emergency medical coverage, for trips of up to 31 days.
Best for WestJet Flyers
First-year value
$536
Annual fee: $139
• Earn 30,000 points on first purchase
• Earn 30,000 points upon spending $5,000 in the first 3 months
• Earn 10,000 points on card anniversary
Earning rates
Key perks
- Annual World Elite Companion Voucher ($119–$499 companion base fare)
- Status Lift: $200 TQS per $5,000 spend (up to 50/year)
- Free first checked bag for cardholder + up to 8 guests
- Exchange option: 30% flight discount, $200 WJ Vacations credit, or 2 lounge passes
Annual fee: $139
• Earn 30,000 points on first purchase
• Earn 30,000 points upon spending $5,000 in the first 3 months
• Earn 10,000 points on card anniversary
Earning rates
Key perks
- Annual World Elite Companion Voucher ($119–$499 companion base fare)
- Status Lift: $200 TQS per $5,000 spend (up to 50/year)
- Free first checked bag for cardholder + up to 8 guests
- Exchange option: 30% flight discount, $200 WJ Vacations credit, or 2 lounge passes
If WestJet is your airline, the WestJet RBC® World Elite Mastercardǂ is the card to hold. Its best perk is the annual companion voucher, which makes it a strong pick for couples and families. In a year you won’t use the voucher, you can trade it for two lounge passes instead.
You’ll earn 2 WestJet points per dollar on WestJet flights, WestJet Vacations and Sunwing Vacations, and on groceries and transportation, including gas, EV charging, public transit and rideshare. Everything else earns 1.5 points per dollar. Every 100 WestJet points is worth $1, so that’s 2% back on those categories and 1.5% on the rest. You also get a free first checked bag on WestJet flights.
The points are worth the most if you fly WestJet regularly. The annual fee is $139, and you’ll need a personal income of $80,000 or a household income of $150,000. Emergency medical coverage lasts 15 days per trip (three days if you’re 65 or older).
If you’d rather keep your options open, Avion points from the RBC® Avion Visa Infinite† transfer to WestJet Rewards too, as well as to other airline programs.
Best for Porter Flyers
First-year value
$1,320
Annual fee: $199First Year Free
• Earn 20,000 points upon spending $5,000 in the first 4 months
• Earn 20,000 points upon spending $9,000 in the first 6 months
• Earn 30,000 points upon spending $18,000 in the first 12 months
Earning rates
Key perks
- Automatic Porter Avid Traveller status
- Free first checked bag + carry-on for cardholder + up to 8 guests
- Complimentary PorterClassic seat selection (rows 8+) for up to 2 passengers
- Priority check-in, security, early boarding
- Priority rebooking during delays
- Round-trip companion pass ($9,000 spend year 1, $50,000 after)
If Porter flies from your home airport, the BMO VIPorter World Elite®* Mastercard®* is built for you. You’ll earn 3 VIPorter points per dollar on Porter purchases, on up to $20,000 a year. With our valuation of VIPorter points at 1.5 cents each, that’s a 4.5% return.
The card also earns 2 points per dollar on groceries and dining (up to $10,000 a year combined), on gas and transportation (up to $5,000 a year) and on hotels (up to $5,000 a year). Everything else, including spending past those caps, earns 1 point per dollar.
The perks make Porter trips easier. You and up to eight guests on the same booking get a free first checked bag and a free carry-on bag. You also get PorterClassic seat selection for up to two passengers, priority airport services and priority rebooking if your flight is delayed.
The annual fee is $199, and you’ll need a personal income of $80,000 or a household income of $150,000. The caps hold back heavy spenders, and the points are worth the most on Porter flights, so the card makes sense only if Porter is an airline you’ll actually fly.
Best Travel Card for Business Owners
First-year value
$1,064
Annual fee: $599
• Earn 70,000 points upon spending $10,500 in the first 3 months
• Plus, earn 25,000 points upon spending $3,500 in month 13
Earning rates
Key perks
- Maple Leaf Lounge access within North America
- Priority check-in, boarding, and baggage handling for cardholder + up to 8 companions
- Free first checked bag for cardholder + up to 8 companions
- Priority airport services at YYZ
- 1,000 SQC per $5,000 spend toward Aeroplan Elite Status (up to 25,000 SQC/year)
- 10% Head Start toward Aeroplan Elite Status (starting 2027)
If your business flies Air Canada, the American Express Aeroplan Business Reserve Card earns 3 Aeroplan points per dollar on Air Canada purchases, 2 points per dollar on hotels and car rentals, and 1.25 points per dollar on everything else. Our valuation of Aeroplan points is 2 cents each, so even the base rate returns 2.5%.
On Air Canada flights, you get priority check-in and boarding and a free first checked bag, and you can earn an Annual Worldwide Companion Pass. Until January 11, 2027, the card includes unlimited Maple Leaf Lounge access within North America for you and one guest.
From January 12, 2027, that access extends to Maple Leaf Lounges and Air Canada Cafés worldwide, still with one guest. The card also adds up to six complimentary Priority Pass lounge passes a year, up to $100 a year towards Air Canada travel in your AC Wallet, and 15% off the points on the base fare of eligible Air Canada flight rewards.
The annual fee is $599 until your first annual fee billing date after January 12, 2027, when it becomes $799. It pays off if you’re on Air Canada several times a year. If your business flies a mix of airlines, the Business Platinum Card from American Express earns points you can move to several programs.
Best Travel Credit Card for Beginners

First-year value
$480
Annual fee: $139First Year Rebate
• Earn 15,000 points on first purchase
• Earn 30,000 points upon spending $3,000 in the first 4 months
Earning rates
Key perks
- 4 Visa Airport Companion lounge visits per year
- Free Skip+ membership with $10 monthly voucher
- NEXUS application fee rebate every 4 years
- Mobile device insurance
- 50% off Disney+ Standard with Ads for 6 months†
The CIBC Aventura® Visa Infinite* Card is an easy first travel card, because its best redemption doesn’t ask you to learn an airline program. You’ll earn 2 Aventura points per dollar on travel booked through the CIBC Rewards Centre, 1.5 points per dollar at gas stations, EV charging stations, grocery stores and drugstores, and 1 point per dollar on everything else.
With the Aventura Airline Rewards Chart, a set number of points covers the base fare of a round-trip economy flight, up to a maximum fare for each region. At the top of the chart, 35,000 points covers a base fare of up to $800, about 2.29 cents per point, with taxes and fees paid separately. For other travel, your points are worth 1 cent each.
You also get four Visa Airport Companion lounge visits a year and a rebate on your NEXUS application fee. Emergency medical coverage lasts 15 days per trip (three days if you’re 65 or older), and trip cancellation covers up to $1,500 per person. The annual fee is $139, and you’ll need a personal income of $60,000 or a household income of $100,000.
Aventura points don’t transfer to airline programs, so the card can’t reach the business class value that programs like Aeroplan offer. Once you’re comfortable with points, a card that earns transferable points, such as the RBC® Avion Visa Infinite†, opens up more options.
Travel Credit Cards: What You Need to Know
When choosing a travel credit card, you should familiarize yourself with what benefits a travel credit card can offer, what features to look out for, and how travel credit cards can fit into an optimized overall credit card strategy.
Why get a travel credit card?
Travel credit cards are the best choice for globetrotters, because the rewards can easily be redeemed above their face value.
Many rewards programs charge a fixed number of points for a wide range of redemptions, so you can increase the value you get for each point by maximizing the program’s sweet spots.
Not every traveller flies on points all the time, and there are plenty of situations where you’ll have to pay cash. Many travel cards give extra rewards on purchases on things like flights, hotels, vacation packages, tours, and other activities.
Even if travel isn’t a major part of your lifestyle, these cards may still be a good choice. Travel cards usually have the biggest signup bonuses, so even if you “cash out” the points for statement credit, they can still be worth more than getting a cash back credit card.
Also, travel cards tend to target the luxury market more than cash back cards. If you’re looking for premium service with your credit card, you’re more likely to find it on a card that earns travel rewards.
What should you look for in a travel credit card?
Not only will you earn points to use for flights and hotels, but good travel cards also come with many perks to enhance the overall travel experience.
Some cards offer ways to improve the ground experience at the airport. These benefits can be used regardless of which airline you’re flying with, or your class of service:
- Priority check-in
- Priority boarding
- Priority baggage handling
- Free NEXUS application
In particular, many premium travel cards come with complimentary airport lounge access:
- All Visa Infinite Privilege cards come with a DragonPass membership and six annual vouchers for free lounge visits
- All World Elite Mastercards come with a DragonPass membership, although the number of annual passes varies
- American Express Platinum cards offer a comprehensive lounge package, including unlimited visits to Priority Pass lounges, Plaza Premium lounges, and more
- All premium Aeroplan cards come with unlimited access to Air Canada Maple Leaf Lounges
- Other cards come with access to the issuing bank or co-branded airline’s flagship lounge
On airline co-branded cards, keep an eye out for airline-specific perks such as:
- Free checked baggage
- Discounted award pricing
- Two-for-one flights, usually in the form of a companion fare
- Easier paths to elite status qualification
These benefits might be a limited-time welcome bonus or achievable every year, possibly with a spending requirement.
In addition, some credit cards don’t charge foreign transaction fees, or have higher rewards on foreign purchases to offset the transaction fees. This saves you up to 2.5% on all of your spending while abroad!
Finally, premium travel credit cards provide a very useful package of travel insurance. Depending on the card, you’d be covered for situations like emergency medical assistance, personal injury in a common carrier accident, trip cancellation or interruption, flight delays or lost luggage, and rental car damage.
What’s the optimal strategy for travel credit cards?
If you’re a dedicated traveller who wants to see as much of the world as possible by maximizing your credit cards, travel credit cards will naturally play an all-important role in your wallet.
Since travel credit cards typically come with more powerful welcome bonuses and benefits compared to other types of cards, you might choose to hold multiple travel credit cards in their wallet at any given time, as long as you’re confident that each card’s bonuses and benefits outweigh their annual fee and are helping you get closer to your travel goals.
Which specific travel credit cards are the best fit for you will depend on your preferred style of travel.
If you’re looking to jazz up your trips in the form of airport lounge access, business class seats, and upgraded rooms and suites at your hotel, then a premium travel credit card will typically deliver enough bonus points, benefits, and elite status opportunities to justify its annual fee.
You could also aim to maximize more than one premium travel credit card at a time, or shrewdly switch up your cards every now and then depending on the best offers on the market. This way, you can scale your earnings and empower an elevated travel lifestyle at a far greater value than the annual fees you’re paying.
On the other hand, even if you’re a budget traveller who doesn’t want to spend too much money, or if you travel infrequently and can’t justify paying annual fees for a travel credit card, you can still make travel credit cards work for you.
You could go with the limited set of benefits on a no-fee credit card, or you could also adopt a strategy like cashing out some of your points for a statement credit on a premium travel credit card to offset the annual fees, and then using the remaining points to fund your travel expenses.
This way, you’re never paying more out-of-pocket than you need to, and you’re using your pure “net winnings” from your credit cards to make your travels go further.
If you travel as a family, then your travel periods are likely limited to peak season in the holidays, and it can be tough to find enough award availability for the whole family to fly on the same flight.
As a result, you might be more interested in credit cards with family-oriented benefits like companion vouchers or perks that extend to supplementary cardholders.
By combining these family-oriented travel strategies with the points you earn from welcome bonuses, you can often book a family trip on a combination of points, cash, and vouchers that save you thousands of dollars compared to paying for everything outright.
As you can see, no matter what type of traveller you are, travel credit cards can help you optimize your travel experience in a way you might not have thought possible before. It’s all about finding the right combination of cards and strategy for maximizing these cards that works the best for you.
Frequently Asked Questions
Below are some questions we frequently hear from readers about the best travel credit cards in Canada.
When do I receive my points on a travel credit card?
Co-branded cards won’t show credit card rewards in your loyalty account until after your monthly statement generates, or a few days later. Meanwhile, with most issuers, in-house rewards show up a day or two after each transaction posts to your account, although you might not receive the bonus points until later.
How do I register for DragonPass?
You can enroll for DragonPass on the Visa Airport Companion website or with the Visa Airport Companion mobile app. Create an account by providing an eligible credit card number. You’ll get a digital membership card with immediate access to participating airport lounges.
Can I transfer my points from one airline to another airline?
No, once your points have been transferred from the bank into an airline’s loyalty program, they’re stuck there until you use them to book a flight. That’s why transferable currencies are so coveted – not just for their value, but for their flexibility.
My plans changed and I won’t be travelling, can I redeem my points for cash back?
It depends on which type of travel points you have. Hotel and airline points can’t be converted to cash, but some programs may let you use your points to buy gift cards or merchandise. Bank programs are more flexible, often with options to also use your points for a cash statement credit. However, all of these redemptions are almost always at a lower rate compared to their potential travel value.
What happens to my points if I cancel a travel credit card?
It all depends on whether the points in question are part of an in-house points program operated by the credit card’s issuing institution, or a third-party loyalty program associated with a co-branded credit card.
Examples of in-house points programs include American Express Membership Rewards, RBC Avion, TD Rewards, Scotiabank Scene+, etc.
In these cases, your points account is typically associated with one particular credit card, and if you were to cancel that card, your points will typically be nullified as well unless you were to transfer them out or use them up beforehand.
On the other hand, you have third-party programs that partner up with a financial institution to issue points-earning credit cards. Examples include Aeroplan, British Airways Avios, Marriott Bonvoy, etc.
For these loyalty programs and their co-branded credit cards, your points are typically transferred to the third-party account with every monthly statement.
If you were to cancel the credit card, nothing would happen to the points you’ve already earned, since they’re now sitting pretty within your loyalty program’s points balance and not associated with your credit card or financial institution in any way.