Canada’s 8 Best Cash Back Credit Cards
Last updated February 13, 2026
Best Cash Back Credit Cards
Cash back rewards are great for their simplicity and flexibility, and anyone can appreciate a little extra money in their bank account.
These are our picks for the best cash back credit cards in Canada.
Compare our picks
Best Flat Rate Cash Back Credit Card
SimplyCash Preferred Card from American Express
- Annual fee
- $9.99/mo
- Welcome bonus
- Up to $250 cash back
- First-year value
- $120
- Top earn rate
- 4% Gas
Best Lifestyle Cash Back Credit Card
Scotiabank Gold American Express® Card
- Annual fee
- $120
- Welcome bonus
- 50,000 Scene+ points
- First-year value
- $455
- Top earn rate
- 6x Groceries
RBC® Cash Back Preferred World Elite Mastercardǂ
- Annual fee
- $120
- Welcome bonus
- Up to $300 cash back
- First-year value
- $200
- Top earn rate
- 3% Groceries
CIBC Dividend® Visa Infinite* Card
- Annual fee
- $120First Year Rebate
- Welcome bonus
- Up to $300 cash back
- First-year value
- $325
- Top earn rate
- 4% Gas
Best Credit Card for Recurring Bills
Scotia Momentum® Visa Infinite +* Card
- Annual fee
- $120First Year Free
- Welcome bonus
- Up to $300 cash back
- First-year value
- $300
- Top earn rate
- 4% Groceries
Best No Fee Cash Back Credit Card
Rogers Red World Elite® Mastercard
- Annual fee
- No fee
- Welcome bonus
- –
- First-year value
- –
- Top earn rate
- 3% US Dollar
Best Cash Back Card with Low Foreign Fees
- Annual fee
- No fee
- Welcome bonus
- –
- First-year value
- –
- Top earn rate
- 0.5x All Purchases
Best Cash Back Credit Card for Everyday Spending
Tangerine® Money-Back World Mastercard®*
- Annual fee
- No fee
- Welcome bonus
- Up to $120 cash back
- First-year value
- $128
- Top earn rate
- 2% Chosen Categories
| Best for | Card | Annual fee | Welcome bonus | First-year value | Top earn rate |
|---|---|---|---|---|---|
| Best Flat Rate Cash Back Credit Card | SimplyCash Preferred Card from American Express | $9.99/mo | Up to $250 cash back | $120 | 4% Gas |
| Best Lifestyle Cash Back Credit Card | Scotiabank Gold American Express® Card | $120 | 50,000 Scene+ points | $455 | 6x Groceries |
| Best Cash Back Mastercard | RBC® Cash Back Preferred World Elite Mastercardǂ | $120 | Up to $300 cash back | $200 | 3% Groceries |
| Best Cash Back Visa Card | CIBC Dividend® Visa Infinite* Card | $120First Year Rebate | Up to $300 cash back | $325 | 4% Gas |
| Best Credit Card for Recurring Bills | Scotia Momentum® Visa Infinite +* Card | $120First Year Free | Up to $300 cash back | $300 | 4% Groceries |
| Best No Fee Cash Back Credit Card | Rogers Red World Elite® Mastercard | No fee | – | – | 3% US Dollar |
| Best Cash Back Card with Low Foreign Fees | Brim Mastercard | No fee | – | – | 0.5x All Purchases |
| Best Cash Back Credit Card for Everyday Spending | Tangerine® Money-Back World Mastercard®* | No fee | Up to $120 cash back | $128 | 2% Chosen Categories |
Best Flat Rate Cash Back Credit Card
First-year value
$120
Monthly fee: $9.99
• Earn 10% cash back on purchases (up to $2,000 spend) in the first 3 months
• Plus, earn $50 cash back upon making a purchase in month 13
Cash back rates
Key perks
- Travel insurance
Monthly fee: $9.99
• Earn 10% cash back on purchases (up to $2,000 spend) in the first 3 months
• Plus, earn $50 cash back upon making a purchase in month 13
Cash back rates
Key perks
- Travel insurance
The SimplyCash Preferred Card from American Express earns 4% cash back on gas and groceries (on up to $30,000 of groceries a year) and 2% cash back on all other purchases. While most cards have higher category rates, this card is unparalleled for everything else.
Plus, the fee is a reasonable $9.99 a month, or $119.88 a year, about the same as other premium cash back cards.
If you prefer a slim wallet and frequently shop at stores that take Amex, this card is without a doubt your best choice.
Best Lifestyle Cash Back Credit Card

First-year value
$455
Annual fee: $120
• Earn 30,000 points upon spending $2,000 in the first 3 months
• Earn 20,000 points upon spending $7,500 in the first 12 months
Earning rates
Key perks
- No foreign transaction fees
- Amex Offers & Front of the Line access
- Get up to 12¢/L in value on fuel purchases at Shell stations°
- Until December 31, 2026, get an additional 3¢/L off at Shell when you pay with your linked card in select provinces and territories^

Annual fee: $120
• Earn 30,000 points upon spending $2,000 in the first 3 months
• Earn 20,000 points upon spending $7,500 in the first 12 months
Earning rates
Key perks
- No foreign transaction fees
- Amex Offers & Front of the Line access
- Get up to 12¢/L in value on fuel purchases at Shell stations°
- Until December 31, 2026, get an additional 3¢/L off at Shell when you pay with your linked card in select provinces and territories^
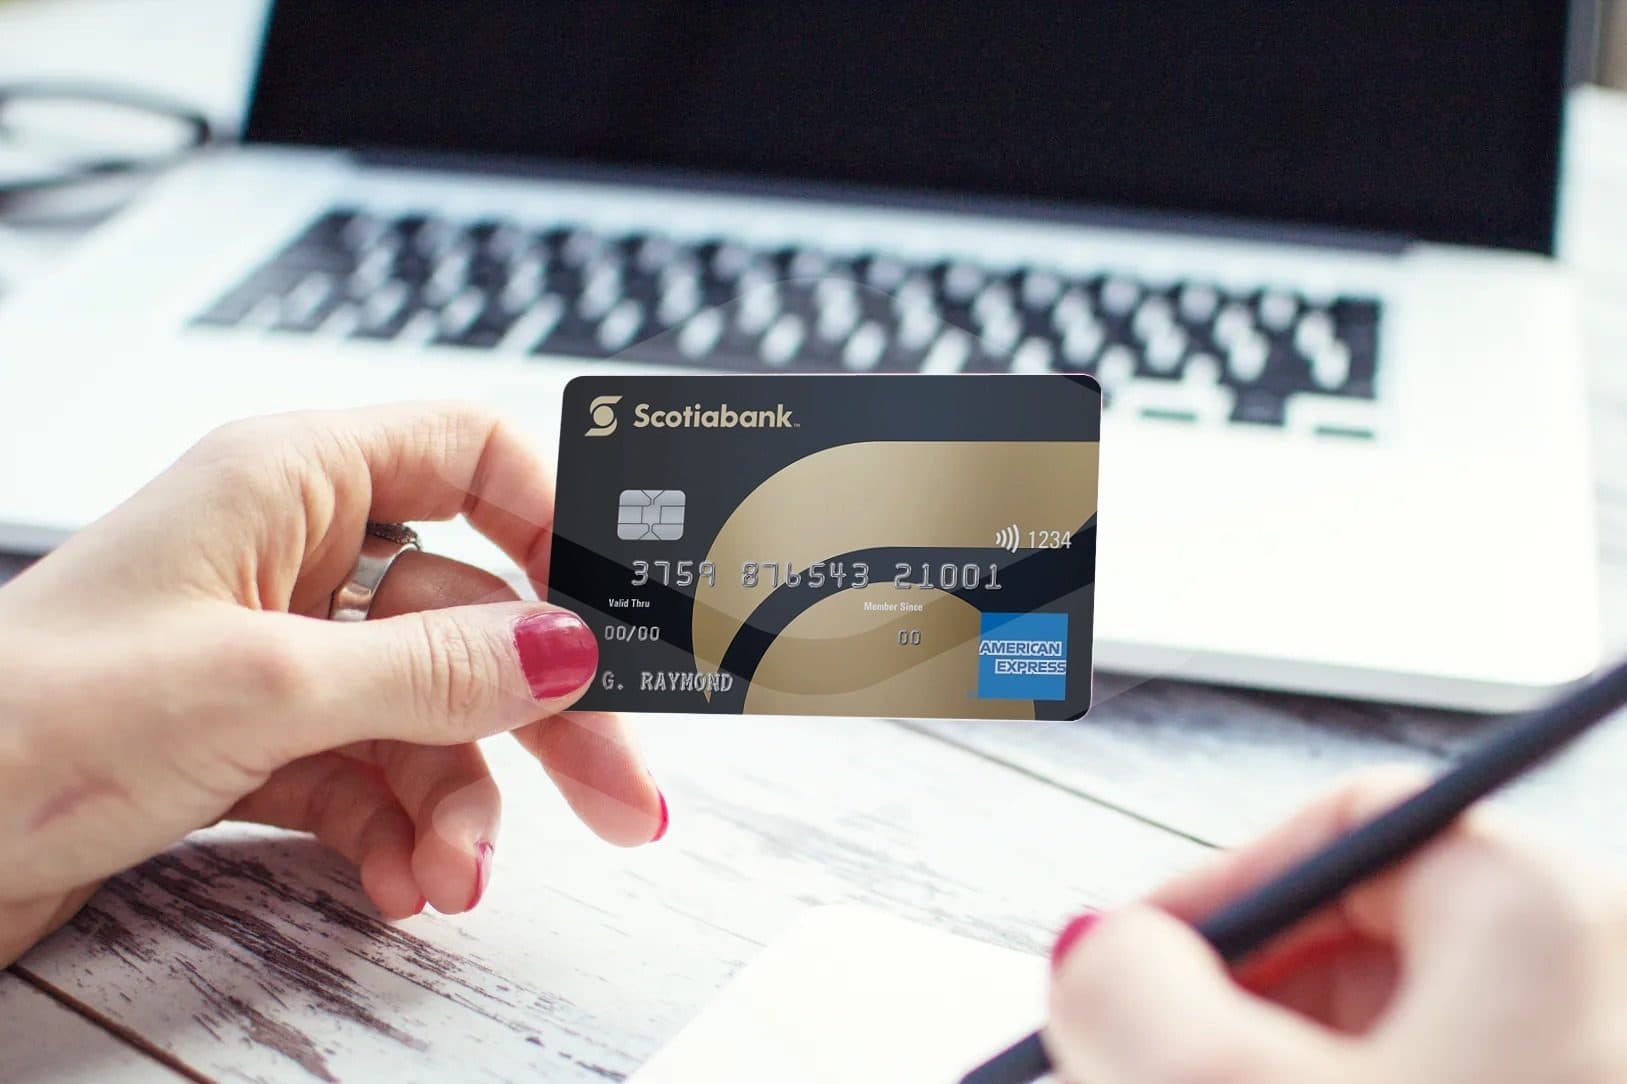
The Scotiabank Gold American Express® Card can’t be beat when it comes to earn rates on everyday spending. If you live a fast-paced lifestyle, this is the ideal cash back card for you.
You’ll earn 6% at Sobeys, IGA, Safeway, FreshCo, and other participating grocers, and 5% on other groceries, restaurants, and entertainment purchases, among the highest rates available on any card. The bonus points are capped at $50,000 spent per year in these categories, setting this card far apart from the competition.
As an added bonus, you’ll get a strong 3% earn rate on gas, transit, and streaming services, no foreign exchange fees, and the many benefits of being an American Express cardholder – including Front of the Line ticket access and exclusive Amex Offers.
While the Scotiabank Gold American Express® Card is technically a travel card, its Scene+ points can be redeemed for cash-equivalent statement credits very easily. If the card’s earn rates and perks fit your needs, it’s absolutely worth considering.
The card's everyday earning rate is what makes it a shining star, so while the welcome bonus is usually quite appealing, I'd treat it like a cherry on top and not let a low welcome bonus hold you back if the card otherwise interests you.
Best Cash Back Mastercard
First-year value
$200
Annual fee: $120
• Earn 15% cash back on purchases (up to $2,000 spend) in the first 3 months
Cash back rates
Key perks
- Petro-Canada 3¢/L savings
- Triangle Rewards 3x Canadian Tire Money
- Rexall Be Well 50 pts/$1
- DoorDash 12-month DashPass
- Mastercard Travel Pass by DragonPass (1,300+ lounges, US$32/visit)
- The Mastercard Collection
The RBC® Cash Back Preferred World Elite Mastercard is one of the strongest cash back Mastercards available in Canada, with a high earn rate across the categories most households spend on every week.
You’ll earn 3% cash back on groceries, dining and food delivery, gas and EV charging, rideshare and transit, and streaming and gaming, and 1% on everything else. With that many categories at 3%, most everyday purchases earn the higher rate, and there are no rotating categories to track.
The welcome offer adds 15% extra cash back for the first three months on up to $2,000 in purchases, worth up to $300 (apply by February 2, 2027). The annual fee is $120 ($50 for an additional card), and the card comes with standard World Elite benefits including extended warranty and purchase protection, plus savings of 3¢ per litre at Petro-Canada.
If you prefer the Mastercard network and most of your spending goes to groceries, dining, gas and getting around, this card sits comfortably at the top of the cash back Mastercard category.
Best Cash Back Visa Card
First-year value
$325
Annual fee: $120First Year Rebate
• Earn 10% cash back on purchases (up to $2,500 spend) in the first 4 months
• Earn $50 cash back on first purchase
Cash back rates
Key perks
- Mobile device insurance
- Free Skip+ membership with $10 monthly voucher
- 50% off Disney+ Standard with Ads for 6 months†
The CIBC Dividend® Visa Infinite* Card is another jack of all trades, with 4% cash back on groceries and gas, and 2% back on restaurants, recurring bill payments, and transit. These are some of the most useful categories for bonus rewards because they typically make up the majority of most Canadians’ everyday purchases.
While other cards may offer similar rewards but with lower annual fees or higher spending limits, none have the same overall mix of category bonuses. If you’re looking for high rates on groceries, gas, and restaurants, don’t want to pay annual fees for more than one premium card, and can’t use American Express where you shop, the CIBC Dividend® Visa Infinite* Card is the total package.
Plus, since it’s issued by a major Canadian bank, you’ll get seamless integration with your chequing account if you also bank with CIBC. Although Desjardins and Meridian have similar cards with a lower annual fee, they don’t have as big of a national presence in case you need customer support.
If you don’t meet the minimum income requirements for this card, you can apply for the CIBC Dividend® Visa Platinum* Card instead. It has all of the same earn rates and fees, just weaker insurance, and only requires an annual personal income of $15,000.
Best Credit Card for Recurring Bills

First-year value
$300
Annual fee: $120First Year Free
• Earn 15% cash back on purchases (up to $2,000 spend) in the first 3 months
Cash back rates
Key perks
- Annual fee waived in the first year.
- Discounts on car rentals through partner programs.
- 10GB of GigSky global mobile data for 15 consecutive days every year, unlimited Travel Essentials by GigSky for select travel apps, plus one 1GB plan for 15 days a year and 20% off further GigSky purchases
- Get up to 7¢/L in value on fuel purchases at Shell stations°
- Until December 31, 2026, get an additional 3¢/L off at Shell when you pay with your linked card in select provinces and territories^
The Scotia Momentum® Visa Infinite +* Card earns bonus rewards on recurring bills. This includes any utility companies that accept credit cards and are set up as a recurring pre-authorized payment, as well as select streaming services. Note that as of October 22, 2026, rent and tax payments earn the regular 1% rate rather than the accelerated rate.
Eligible recurring transactions earn 4% cash back. That’s by far the highest available earn rate for your recurring bills. Also, with 4% cash back on groceries, this card is a great choice for families with many mouths to feed and large homes to heat.
Plus, new cardholders can often find an offer for their first-year annual fee waived and 15% cash back in the first three months, on up to $2,000 in purchases.
Best No Fee Cash Back Credit Card
No annual fee
Cash back rates
Key perks
- No annual fee
- World Elite Mastercard travel benefits
No annual fee
Cash back rates
Key perks
- No annual fee
- World Elite Mastercard travel benefits
If you’re looking for a simple solution, the Rogers Red World Elite® Mastercard® is the card for you. While other cards offer better category earn rates, there’s no better choice for a budget-conscious spender.
The card earns 2% cash back on all purchases if you're an eligible Rogers, Fido, or Shaw customer, or 1.5% cash back if you're not. This rate is slightly higher than the de facto benchmark for other World Elite Mastercards, but the Rogers Red World Elite® Mastercard® has the advantage of having no annual fee. If you’re primarily concerned about keeping costs down, you won’t find another card with a better all-round cash back rate.
Also, the card gives higher rewards on US-dollar purchases to offset the foreign exchange fee. This gives you peace of mind not to fret about extra costs if you’re doing any online shopping on US sites or going for a jaunt over the border.
If you're an eligible Rogers, Fido, or Shaw customer, you'll get 50% bonus cash back when you redeem for a Rogers, Shaw, or Fido purchase. This results in an effective 3% cash back earning rate on all purchases. The bonus ends on November 18, 2026. From then, cash back redeems at face value, and eligible Rogers purchases, such as a Rogers or Fido mobile bill, earn up to 5% instead.
Whether you like the simplicity of only using one card, or a high earn rate on uncategorized spending at no extra cost, there’s a place for the Rogers Red World Elite® Mastercard® in every wallet.
Best Cash Back Card with Low Foreign Fees
No annual fee
Earning rates
Key perks
- 1.5% foreign transaction fee (vs standard 2.5%)
- Mobile device protection
No annual fee
Earning rates
Key perks
- 1.5% foreign transaction fee (vs standard 2.5%)
- Mobile device protection
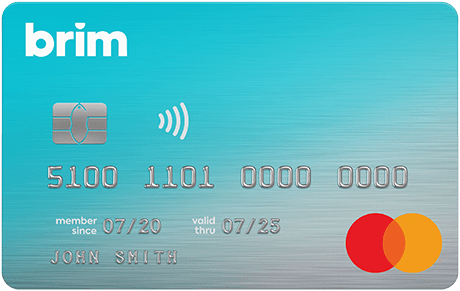
Brim is a small credit card issuer with lower foreign transaction fees on many of their cards. Their entry-level card with no annual fee, the Brim Mastercard, makes a great keeper or backup card for reducing foreign transaction fees, as it charges 1.5% instead of the industry-standard 2.5%.
This card earns equal rewards on all foreign purchases, a unique feature among cards with no annual fee. Also, as a Mastercard, you’ll find it’s very widely accepted around the world on all your foreign purchases.
For zero foreign transaction fees, you'd want a card from the No FX Fee page – but if you're a cash back earner who shops abroad occasionally, the Brim's 1% saving per transaction adds up. Even for use at home, you’ve got a decent all-round entry-level credit card in the Brim Mastercard.
Best Cash Back Credit Card for Everyday Spending
First-year value
$128
No annual fee
• Earn $120 cash back upon spending $1,500 in the first 3 months
• Plus, get a 1.95% promotional interest rate on balance transfers for six months with a 1% balance transfer fee
Cash back rates
Key perks
- No annual fee
- Mobile device insurance up to $1,000
- Rental car collision damage waiver
- Purchase assurance and extended warranty ($60,000 lifetime maximum)
- FlexiRoam global data
- Scene+ members earn 1 point a litre, or 2 a litre on V-Power with Scene+ linked to Shell Go+. The extra 4¢/L V-Power discount is only for Tangerine cards that earn Scene+ points.
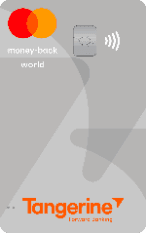
The Tangerine® Money-Back World Mastercard®* stands out for combining no annual fee with a generous 2% cash back rate in up to six spending categories of your choice, including groceries, gas, dining, recurring bills, and transportation.
That flexibility sets it apart from most cash back cards, which lock you into predetermined categories. You choose where you earn the most, and everything else earns 0.5%.
The welcome offer of $120 cash back when you spend $1,500 in the first three months adds a nice starting bonus. You'll also get World Mastercard benefits like mobile device insurance – a perk that most no-fee cards don't include.
For a card with no annual fee, the Tangerine Money-Back World delivers an impressive combination of earning potential, flexibility, and everyday practicality.
Cash Back Credit Cards: What You Need to Know
When choosing a cash back credit card, you should familiarize yourself with what benefits a cash back credit card can offer, what features to look out for, and how cash back credit cards can fit into an optimized overall credit card strategy.
Why earn cash back rewards?
Cash back cards are great for one simple reason: cash is king. You’re not locked into using your rewards at one particular store or brand, and you can get immediate value for your rewards rather than waiting several months to take a trip you just booked on points.
Plus, cash is easy to understand, and the value of your rewards is plain as day. You may prefer to use cash back credit cards if you’d rather not spend time learning the rules of a complicated loyalty program just to reap the benefits of your credit card.
Even for frequent travellers, cash gives you unparalleled flexibility as you book your travel arrangements. You can use it for airlines that aren’t part of an alliance, offbeat accommodations, or car rentals. In fact, you can subsidize your trips however you like, using cash rewards for anything like public transportation, excursions and experiences, dining, or souvenirs.
What should you look for in a cash back credit card?
One major advantage of premium cash back cards is that they tend to have significant bonus rewards for spending in specific categories. For example, many Visa Infinite cards offer 1% cash back on most purchases, but 4% cash back at grocery stores.
Other cards instead offer the same cash back rate on all purchases. These cards are simple, and it’s easier to stay organized with them. They’re good for miscellaneous purchases, as they usually have a higher flat rate than non-bonused spending on cards with bonus rates.
It’s rare to find a one-size-fits-all cash back card. If you care about maximizing your rewards on everyday spending, you’ll likely want at least two or three of these cards, where each one covers the others’ weaknesses. That way, you’ll get high cash back rates on as many categories as you can.
On the other hand, if you’d prefer the simplicity of only managing one card at a time, the best cash back card will depend on your spending habits.
Cash back cards also offer some premium benefits, even though they aren’t travel cards with a full-fledged suite of travel perks. Indeed, cash back cards are often still useful for travellers:
- Cash Back Visa Infinite cardholders still get all of the same benefits as Visa Infinite travel cards, including Concierge services and the Luxury Hotel Collection.
- Cash Back World Elite Mastercard members still get all of the same benefits as World Elite travel cards, including a DragonPass membership and a FlexiRoam eSIM for international data roaming.
- Many cash back cards provide purchase protection insurance, and some even provide various types of travel insurance.
- Some cash back cards waive foreign transaction fees.
- Some cash back cards have unique services that aren’t found on travel cards, such as roadside assistance.
What’s the optimal strategy for cash back credit cards?
When it comes to maximizing credit cards as a whole, cash back credit cards typically play a more supplementary role in a savvy credit card user’s wallet compared to travel rewards credit cards.
That’s because the main appeal of a cash back credit card is its simplicity and ease of use: you get a certain percentage of cash back as a reward for your spending.
In exchange, however, the overall upside of your rewards is limited: you’ll be able to get 1.5–2% back on your spend, but the potential outsized return of travel rewards (5%, 10%, or even more!) isn’t accessible to you.
If you’d like to get the best of both worlds, consider a travel credit card that earns “cash equivalent” points rewards. For example, the American Express Cobalt Card and the Scotiabank Gold American Express® Card both offer sky-high 5% earning rates on groceries, food, and drinks – you’ll never get these types of rewards on a regular cash back credit card.
Technically, these two credit cards earn points rather than cash back: Amex Membership Rewards points and Scene+ points, respectively. However, both can be redeemed at 1 cent per point against travel purchases.
Since a statement credit is basically as good as cash in your pocket, these two credit cards (and others that can be used the same way) can be thought of as more powerful versions of a traditional cash back credit card.
And who knows, since Amex MR points can also be transferred to flight and hotel programs and redeemed for some awesome experiences, you may even find yourself swayed by the power of travel rewards once you start dabbling with these cards!
Overall, traditional cash back credit cards are best suited to credit card users who prefer to keep things as simple as possible. If you’d like to “set it and forget it” in terms of your credit card strategy, you might go with a simple cash back card and call it a day.
But for credit card users who are looking to optimize, cash back credit cards alone probably won’t cut it in terms of the welcome bonus or the regular return on spending.
Frequently Asked Questions
Below are some questions we frequently hear from readers about the best cash back credit cards in Canada.
When can I redeem my cash back rewards?
Many cards let you request cash back to be issued as a statement credit any time you’ve accumulated enough rewards. Depending on the card, you can do this online or over the phone, or rewards may be paid automatically.
Some cards only pay out monthly, quarterly, or yearly. If you have one of those cards, make sure you’re never counting on your cash back urgently, and don’t be alarmed if it isn’t credited immediately after each purchase.
I prefer the earn rates and perks of travel credit cards more than cash back credit cards. Can I redeem travel rewards for cash back?
Some travel cards let you redeem points for statement credit to cover any travel expense, including refundable bookings. Examples include credit cards that earn Scene+ points , MBNA Rewards points, or American Express Membership Rewards points.
By making a refundable booking, covering the expense with your points, and then refunding the booking, you can therefore “cash out” your points. If you can use your points this way, they’re effectively as good as cash back.
Other types of travel rewards may let you redeem for cash back, but often at a very poor rate when compared to flights or hotels. In these cases, it’s better to redeem points directly towards your travel plans.
Whichever type of credit card you apply for, make sure you think about the value you expect to redeem the points for, before you submit your application.
How do I know if my purchase counts as a recurring bill payment?
Recurring bill payments are unlike other purchases. To get the bonus rate, they have to be set up as an automatic charge to your credit card, with a pre-authorization on file with the biller.
If you make a manual payment every time you receive your monthly utility bill, you likely won’t receive the recurring bonus rate, even if it’s the same amount every time.
Some banks, like Scotiabank, also have partnerships with specific merchants. If you have any questions about what qualifies as a recurring payment, it’s best to contact the credit card issuer for clarification.